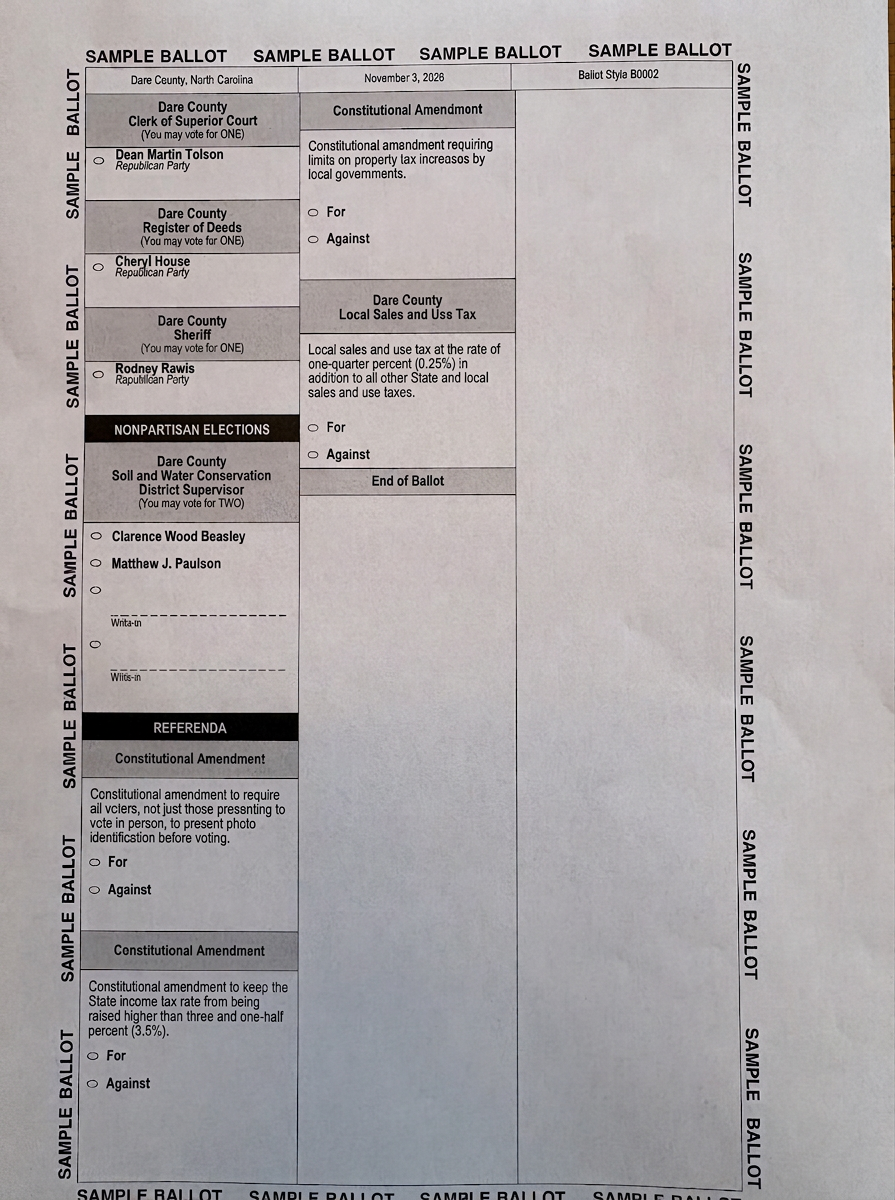
To decide how to vote on three proposed amendments to the N.C. State Constitution that appear on the back of the Nov. 3 ballot (see above), a voter needs to do some research.
Knowing how unlikely it is that voters will do that—even those who enjoy doing research—The Beacon has done it for you.
Before we run through the origin, intent, effect, and arguments, pro and con, of the three proposed amendments, we will first remind you that early voting starts tomorrow (See The Beacon, 10/9/26 for polling places and times of operation) and answer a basic question:
How does a N.C. State Constitutional amendment get on the ballot?
The answer is that a 60 percent vote (3/5) of the entire N.C. General Assembly, taken during one legislative session, is required. That computes to 72 votes in the 120-member N.C. House of Representatives and 30 votes in the 50-member N.C. State Senate, assuming there are no vacancies.
Amendments do not require the Governor’s signature to be referred to the ballot. They originate like all State legislation does, as either a Senate bill or a House bill.
We will address each proposed amendment in the order in which they appear on the Referenda section of your ballot. In each case, you vote “For” or “Against.”
THE PROPOSED AMENDMENTS
- “Constitutional amendment to require all voters, not just those presenting to vote in person, to present photo identification before voting.”
This amendment to Section 3 of Article VI of the N.C. State Constitution was Senate Bill 921.
BACKGROUND: In 2018, as you may recall, N.C. voters approved a constitutional amendment requiring all in-person voters to present a photo ID. All Republican legislators voted in favor of this amendment, and all Democratic legislators voted against it. Voters approved it, 55.49 percent to 44.51 percent.
Litigation contesting the constitutionality of the amendment delayed its implementation. It was only after a newly elected Republican-majority N.C. Supreme Court revisited in 2023 its previous decision in Holmes v. Moore in 2022 to strike down the amendment as unconstitutional that the photo-ID requirement became enforceable.
We believe the legal history of the 2018 constitutional amendment is as confusing as the photo-ID requirement itself.
If an in-person voter does not have a valid form of photo ID, that person can still vote a provisional ballot and complete an ID Exception Form, which lists “reasonable impediments” to showing an ID, one of which he or she must choose. We will not belabor these impediments. (See N.C. State Board of Elections at https://www.ncsbe.gov/voting/voter-id or the Dare County Board of Elections at https://www.darenc.gov/departments/elections/election-information.)
In 2024, the State legislature extended the photo ID requirement to voters using mail-in absentee ballots. N.C. law now requires mail-in voters to include a photocopy of an acceptable ID with their ballot or to complete and send in an ID “exception form,” offering the same choices of “impediments” as in-person voters have.
N.C. law also allows mail-in voters who are unable to attach an ID photocopy to provide their driver’s license number or the last four digits of their Social Security number as a substitute.
HOW WOULD APPROVAL OF THE AMENDMENT CHANGE CURRENT LAW?
In short, it would not. What it would do, however, is codify the existing mail-in rule in the N.C. State Constitution, rather than leaving it as a matter of State statute.
Constitutional amendments can only be changed by future constitutional amendments, not by ordinary legislation, hence they should not be approved lightly.
VIEWPOINTS
Katelin Kaiser, policy director of Democracy North Carolina considers this amendment “another attempt to disenfranchise voters by mail . . .. Legislative leadership has made it more difficult for students, older people, and people who are disabled to vote by mail in North Carolina.”
But N.C. Senator Warren Daniel (R-46) counters: “Voter ID is a commonsense measure that needs to apply equally to all voters. . . . We shouldn’t treat one form of voting differently, and our constitution should reflect that.”
The Beacon’s view is that the N.C. State Constitution should never have been amended for something that can be, and is, manageable by State statute. We should not hamstring future State legislatures by extending the constitutional restriction.
- “Constitutional amendment to keep the State income tax rate from being raised higher than three and one-half percent (3.5%).”
This amendment to Section 2 of Article V of the N.C. State Constitution was Senate Bill 1080.
BACKGROUND: In 2018, N.C. voters approved a constitutional amendment that lowered the maximum allowable state income tax rate from 10 percent to 7 percent. It was approved by a margin of 57.35 percent to 42.65 percent.
Now Republicans in the legislature seek to reduce the maximum tax rate by 50 percent and to codify that extreme reduction in the N.C. State Constitution.
All Republicans in the General Assembly approved Senate Bill 1080, and all Democrats opposed it, except one, who did not vote.
The North Carolina personal income tax rate has been gradually declining since 2023, pursuant to enactment on Oct. 3, 2023, of House Bill 259, which reduced the tax rate from 4.76 percent in 2023 to 3.99 percent in 2026.
North Carolina currently has a flat personal income tax rate of 3.99 percent, which, conceivably, would go even lower in the ensuing years.
Starting in 2027 and continuing through 2034, if general revenue fund rates are met, the tax rate will be lowered to the greater of 1) the prior year’s tax rate decreased by one-half percentage point or 2) 2.49 percent. (See “Part XLII, Finance”; subsection “Personal Income Tax Rate Reductions,” in Session Law 2023-134, H.B. 259, at https://www.ncleg.gov/EnactedLegislation/SessionLaws/HTML/2023-2024/SL2023-134.html.)
Why, you might ask, are Republicans seeking to undermine the flat-tax system that they set up in the State budget bill just three years ago?
We will let Governor Josh Stein (D) answer that question first:
VIEWPOINTS
The amendment, Governor Stein says, is “a con, a cynical shell game and a millionaire protection cap. It will not put any more money in anyone’s pockets. But what it will do is make regular people pay the consequences of it next year and years into the future because it will insulate the very wealthy from ever having an increase in their income tax.
“We have to have a balanced budget every year when revenues are needed. You know who’s going to have to pay? It’s you. Regular people every time they go buy something through the sales tax.”
There is no maximum allowable sales tax rate codified in the N.C. State Constitution. If income-tax revenues fall short, isn’t it likely that sales taxes will have to increase?
Says State Senator Michael Lee (R-7): “Our tax reforms have produced more than a decade of strong revenue growth while letting people keep more of what they earn, and this amendment locks in that progress. . . . [This is] a chance to put a real, lasting protection in the constitution for every taxpayer in the state.”
It seems to The Beacon that the legislature has already done that for the next eight years, and there is no compelling reason to alter the State Constitution now.
As of mid-2026, seven states had enacted income-tax surcharges or special top tax brackets that apply only to high-income taxpayers, typically those who earn at least $1 million annually. They are California, New Jersey, New York, Washington, Massachusetts, Maine, and Rhode Island.
Washington voters will vote Nov. 3 on whether to repeal that state’s “Millionaire Tax,” which is designed to take effect Jan. 1, 2028. The new law imposes a tax of 9.9 percent on households earning more than $1 million.
- “Constitutional amendment requiring limits on property tax increases by local government.”
This amendment to Section 2 of Article V of the N.C. State Constitution was House Bill 1089.
BACKGROUND: The votes in both chambers of the General Assembly were “nearly party-line,” writes the N.C. League of Municipalities in its May 22, 2026 Legislative Bulletin.
All Republicans, and two delegates who switched their party affiliation from Democrat to Unaffiliated, voted in favor of the amendment, according to the League of Municipalities, and all Democrats, except one who was absent, voted against it.
In the Senate, Democrat Dan Blue (Wake) joined Republicans in approving the amendment, and three other Democrats were absent for the vote.
The primary sponsors of H.B. 1089 were Republicans from Cabarrus and Catawba counties, which are in the Charlotte area; Davie County, which is near Winston-Salem; and Wake County (Raleigh).
WHAT DOES THE AMENDMENT ACTUALLY SAY? VIEWPOINTS?
The proposed constitutional amendment adds the following sentence to subsection 5 of Article V, Section 2:
“The General Assembly shall enact general laws limiting the amount by which the levy of taxes on property may increase, which may include exceptions.”
If voters approve the amendment, the General Assembly would have to pass laws limiting the maximum amount property taxes may increase. The means by which it would do that are not set forth in the amendment, and there is no explanation of what is meant by “exceptions.”
According to the Carolina Journal, online May 1, 2026, “Supporters say the amendment is needed to rein in rapid growth in property tax collections over the past few years. They argue a cap would provide predictability for homeowners and businesses while forcing local governments to better control spending.
“Critics,” the article by Andrew Pomeranz continues, “have raised concerns that a state-imposed cap could constrain counties’ and municipalities’ ability to fund essential services, including public schools, emergency response, and infrastructure. They also argue the amendment would shift power away from locally elected officials and toward the General Assembly.”
With this amendment, the State legislature is clearly intruding into an area of government that has always been the province of municipal authority. It is seeking to usurp local control.
We also think it’s obvious that what’s good for Raleigh may not be good for Southern Shores or for Fayetteville or for Asheville or for any other municipality in our large, diverse state, just as it’s obvious that rural areas have different needs than urban areas.
If taxpayers want to influence the property tax rates in their municipalities, they need to elect local officials who will do their bidding and vote out those who don’t.
JUST A WORD ABOUT THE PROPOSED COUNTY SALES TAX INCREASE:
We don’t think you need to do much research to figure out whether you support a quarter-cent increase in the county sales tax. We would just mention that in the public forums he has held recently to bring the issue to the people, Dare County Manager/Attorney Bobby Outten has said that the sales-tax increase would likely generate $6 million more in revenue, which would enable the County to borrow $57 million to renovate and expand Parks & Recreation facilities.
See “At community sales tax meeting, pickleball takes center stage,” The Outer Banks Voice, Oct. 8, 2026.
By Ann G. Sjoerdsma, The Southern Shores Beacon, 10/14/26

